Cash Yields Are Back. Inflation Never Left.
The Fed just raised interest rates for the first time since 2023, and your cash is finally earning again. Here's why higher yields alone won't protect your retirement from rising prices - and what each of your buckets should do about it.
For the first time in more than three years, the Federal Reserve did the one thing it spent 2023 through 2025 working hard to avoid: it raised interest rates. On September 16, the Federal Open Market Committee lifted its benchmark rate to a range of 3.75% to 4% — the first hike since 2023 — and made clear it may not be the last. A strong majority of officials now pencil in at least one more increase before year-end.
If you’re retired or standing at the edge of it, this week probably felt like a whipsaw. Stocks slipped, the Dow logged its worst week since March, bond yields climbed, and the business press swung from “rate cuts are coming” to “brace for more hikes” almost overnight. So let me say the calm part out loud: a single Fed meeting is weather, not climate. It changes what your cash earns and what your groceries cost — but it does not require you to tear up a retirement plan that was built to hold in exactly this kind of environment.
Here’s what actually changed, and what it means for the money you’re living on.
What the Fed did — and why it matters now
The Fed’s job is a balancing act between two risks: an economy that runs too hot (inflation) and one that runs too cold (unemployment). For most of the last two years the worry was cooling growth, so rates drifted lower. This month the worry flipped. A fresh run-up in oil prices — driven largely by conflict in the Middle East — has pushed inflation warm enough that the committee decided it had to lean against it. You can read the Fed’s own policy statement and projections for the full reasoning, and track the underlying prices through the Bureau of Labor Statistics’ Consumer Price Index.
The important word for retirees isn’t “hike.” It’s “again.” After a long stretch of expecting cheaper money, we’re back in a world where borrowing costs more and cash pays more at the same time. That combination cuts in two directions, and most coverage only tells you about one of them.
The good news: your safe money is finally being paid
For years, the money you kept safe — checking, savings, money market funds, short-term Treasuries — earned almost nothing. Keeping a year or two of spending in cash meant accepting a near-zero return as the price of sleeping at night. That tax on caution is largely gone.
With the Fed’s rate near 4%, the yields on money market funds, high-yield savings accounts, short-term Treasury bills, and CDs have moved up in step. You can see current government rates directly at TreasuryDirect. For someone drawing income in retirement, that’s a genuine improvement: the Now bucket — the near-term cash you spend from — can sit in something that actually earns while it waits. Being conservative with your first year or two of expenses no longer means being punished for it.
The catch: paying more isn’t the same as keeping up
Now the part the headlines skip. A yield is a nominal number. What your money is worth is a real number — nominal yield minus inflation. And the reason the Fed raised rates in the first place is that inflation is running warm again.
So if a money market fund pays around 4% and the cost of the things you actually buy — groceries, insurance, utilities, a tank of gas — is climbing at a similar pace, your “raise” on cash can be quietly eaten before it reaches you. The number in the account goes up. The purchasing power behind it barely moves. This is the same dynamic I wrote about in how inflation hits each retirement bucket differently: cash feels safe, but against sustained inflation it is one of the more exposed places to park money you won’t touch for years.
Thomas’ Take: “Safe” and “protected” are not the same word. Cash protects you from market swings. It does not protect you from the slow leak of rising prices. In a higher-rate, higher-inflation stretch, the risk isn’t a crash — it’s erosion you don’t notice until a few years have passed.
A hypothetical: cash that pays, and still slips
Consider a hypothetical case. Ellen, 68, retired two years ago from a career in school administration outside Kansas City. Following a bucket approach, she keeps about $120,000 in her Now bucket — roughly two years of spending — in a money market fund. A year ago that cash earned her almost nothing. Today, at about 4%, it throws off roughly $4,800 a year.
That looks like a clear win, and in one sense it is. But over the same year, her grocery bill, her homeowner’s insurance, and her utilities each rose somewhere in the 3% to 4% range. Run the two forces together and Ellen’s cash is earning more and treading water: the extra yield is close to being offset by the higher cost of the life that cash is supposed to fund. (These are round, illustrative figures, not a forecast — your own numbers will differ.)
The lesson isn’t “cash is bad.” Ellen needs that Now bucket; it’s what keeps her from selling investments in a down week. The lesson is that cash is a holding pen for money you’ll spend soon, not a growth engine and not a hedge against years of rising prices. Once you see it that way, the higher yield is a nice bonus on money that was always meant to be temporary.
What it means for each bucket
This is exactly why I organize retirement money into Now, Soon, and Later buckets rather than one undifferentiated pile. A rate hike lands on each bucket differently:
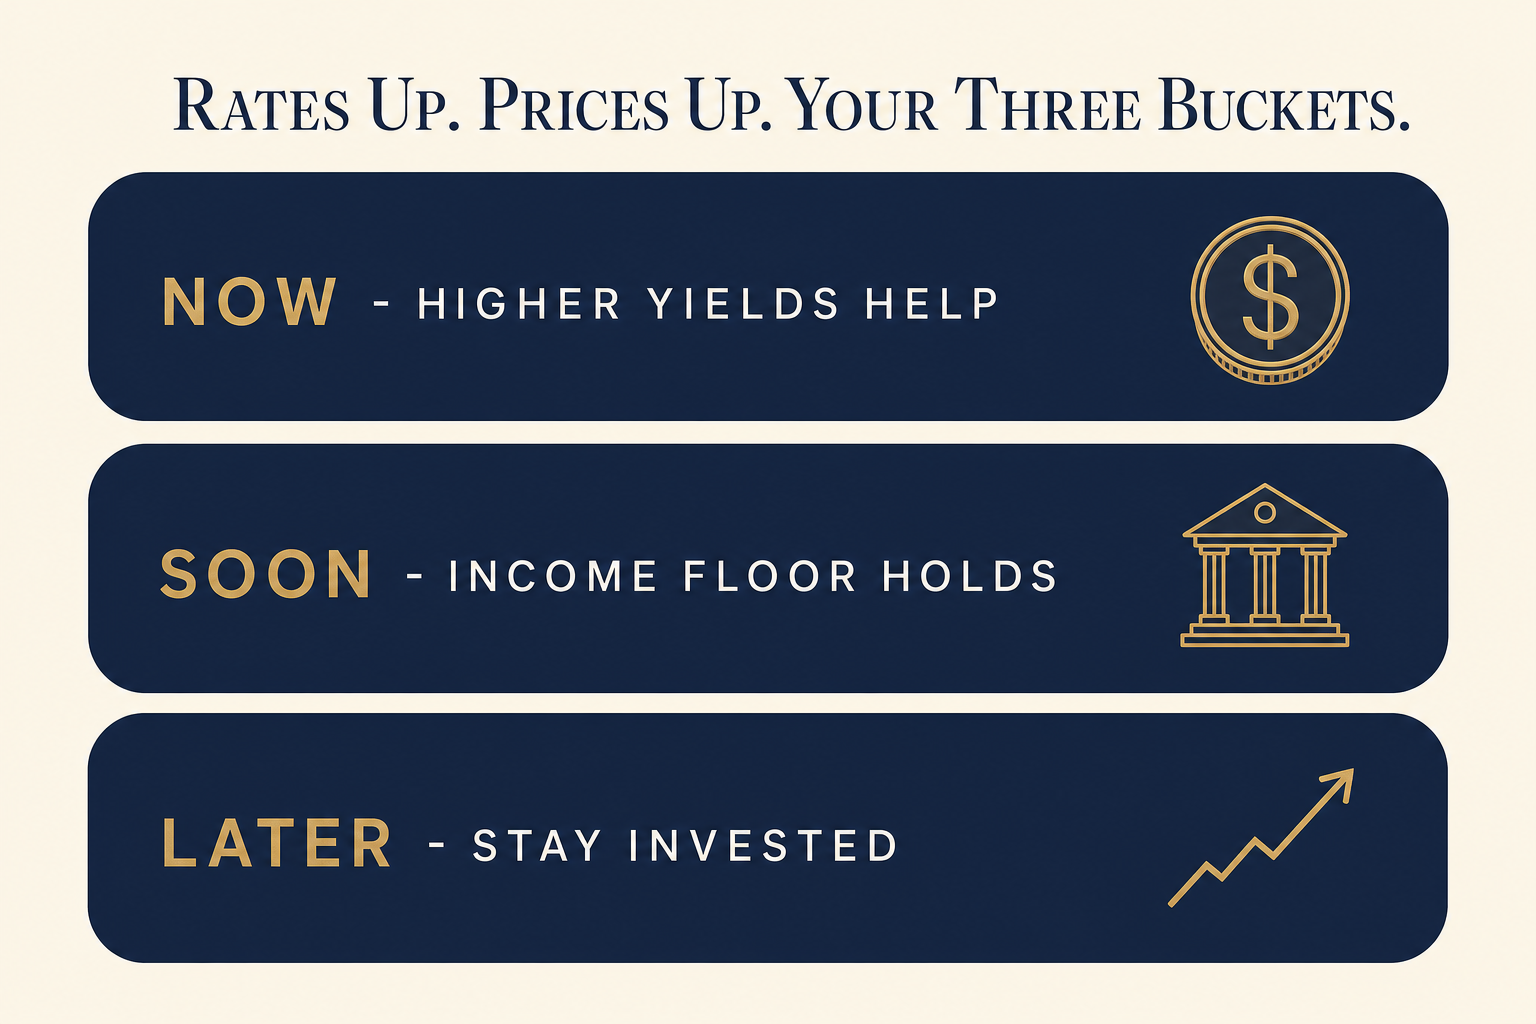
Now (near-term cash). The clear winner from higher rates. Keep it liquid, let it earn what it now earns, and don’t be tempted to chase yield by stretching this money into things that can lose value right when you need it.
Soon (your guaranteed income floor). This is your real defense against inflation eroding your lifestyle, and it barely cares what the Fed did this week. Social Security comes with an annual cost-of-living adjustment — though, as I covered in the 2027 COLA breakdown, that adjustment doesn’t cover everything. Pensions and income-focused fixed index annuities can round out a floor of dependable income that arrives whether rates rise or fall. The point of the Soon bucket is that the essentials are covered by money that doesn’t flinch at a headline.
Later (long-term growth). The bucket most people panic about on a red day, and the one that needs the least tinkering. Its whole job is to outrun inflation over a decade or more, and a quarter-point move doesn’t change that mission. Selling growth assets because the Fed nudged rates is how a temporary dip becomes a permanent loss.
Don’t rebuild your plan around one meeting
The instinct after a surprise hike is to do something — shift everything to cash, bail out of stocks, lock in a rate before it moves again. Resist it. I made this case in more detail in why you shouldn’t time the market around the Fed, and this week doesn’t change the conclusion. Reacting to a single meeting is how good plans get wrecked by short-term noise.
What a moment like this is good for is a checkup. Is your Now bucket actually earning what it could? Is your Soon-bucket income floor large enough to cover the essentials if inflation stays warm for a while? Is your Later bucket positioned for years, not for this week? Those are the questions worth sitting with — not “what will the Fed do at the next meeting,” which nobody can answer, including the Fed.
If you want to pressure-test your own plan against a world of higher rates and stickier prices, it’s worth modeling with your real numbers rather than a straight line in your head. A planning tool like ProjectionLab lets you run different inflation and interest-rate assumptions and watch whether your income floor and reserves actually hold up. (ProjectionLab is a paid tool; the link is an affiliate link, which means I may earn a small commission at no extra cost to you. I only recommend tools I’d use myself.)
Rates went up. That’s real, and for your cash it’s even a little welcome. But a durable retirement plan was never built to win or lose on one Fed meeting — it was built so that no single meeting gets to decide how your year goes. If yours is doing its job, the honest response to this week is a nod, a quick look at your buckets, and back to your life.
This article is published by Confluence Media Group LLC, an independent publisher of educational financial content. Thomas Clark is a Series 65 Investment Advisor Representative. The information provided is for educational and informational purposes only and is not personalized financial, tax, or legal advice. Past performance does not guarantee future results. All investing involves risk, including potential loss of principal. Consult a qualified professional before making financial decisions.
Confluence Media Group LLC is a separate entity from Confluence Capital Management, the investment advisory practice through which Thomas Clark provides advisory services. Advisory services are not offered through this publishing platform.
About Thomas Clark
Thomas Clark is the founder of Confluence Media Group LLC and a Series 65 Investment Advisor Representative. He has spent nearly two decades working with families on retirement planning, with a focus on Social Security optimization, retirement income coordination, and the bucket planning approach to building a guaranteed income floor.
Thomas writes and publishes at thomasclarkadvisor.com and is the author of The Just in Case Binder — a 148-page printable family financial organizer for households who want to make sure the people they love know where everything is.
He lives in North Carolina with his family.
Subscribe to the weekly newsletter · Get the Just in Case Binder

Thomas Clark is a Series 65 licensed investment advisor and experienced trader. He specializes in investing, retirement planning, and market analysis, helping individuals build wealth and make informed financial decisions.
