The Nasdaq Hit a Correction. Your Income Floor Didn’t.
The Nasdaq entered a correction last week while a strong October jobs report rattled markets. Here's what the week actually changed for your retirement income.
Last Thursday, the Nasdaq fell 5.5% in a single session — its worst day since April 2025 — and crossed into what Wall Street calls a correction. The “Magnificent Seven” technology giants shed more than $1 trillion in combined value in a day. By the weekend, the headlines had decided it was a crisis.
I want to make a different argument. The most important number last week wasn’t the one that scared everybody. It was a quieter one, released the next morning in the October jobs report. And if you’ve built your retirement around a guaranteed income floor, that quieter number is the one that actually touches your life.
What actually happened last week
Here are the facts, because the facts are calmer than the headlines. On Thursday, November 5, the tech-heavy Nasdaq dropped about 5.5%, the S&P 500 fell roughly 4.4%, and the Dow shed more than 1,800 points. The Nasdaq closed about 11% below its October 6 record, which is the technical definition of a correction: a decline of 10% or more from a recent high.
The damage was concentrated. The small group of AI-linked megacaps that carried the market up all year lost more than $1 trillion of market value in that one session, with the largest chipmaker alone shedding over $440 billion and falling more than 9% on the day. On Friday, the Nasdaq bounced back about 1.1% as some of those names recovered. For the full week, the Nasdaq was down about 3.4% — its fourth straight weekly decline — while the Dow fell less than 1%.
That gap is the first thing worth noticing. The Dow barely moved on the week; the Nasdaq is in a correction. Same five days, very different experiences, depending entirely on how much of a handful of AI names you were holding. I wrote about this split a few weeks ago, and it only got sharper: a market this concentrated doesn’t fall evenly, and it doesn’t rise evenly either.
Why a good jobs report spooked the market
Then came Friday. The October jobs report showed employers added about 165,000 jobs — roughly double what economists expected — with the unemployment rate at 4.1% and wages up about 3.1% from a year earlier. A strong economy. Good news.
Stocks didn’t treat it as good news, and that confuses people every time it happens. Here’s the mechanism in plain language. When the job market runs hot, the Federal Reserve worries that inflation won’t keep cooling, so it leans toward keeping interest rates higher — or raising them further. After Friday’s report, futures markets were pricing in roughly a 3-in-4 chance that the Fed raises rates again at its December 8–9 meeting, from a target range that currently sits at 3.75% to 4.00%. Higher rates make the rich valuations on fast-growing tech stocks harder to justify, so money rotates out of them. Good news for Main Street, a headwind for the most expensive corner of Wall Street.
This is the “good news is bad news” reflex, and it’s a stock-market story. I’d argue it buried the more important one.
The number that mattered more
Set the Nasdaq aside for a second and look at what that same report does to the safe side of a retirement plan.
A hot labor market and a Fed inclined to hold rates higher means the yield on cash, Treasury bills, CDs, and the income riders on fixed index annuities stays elevated. For most of the 2010s, “safe” money paid a rounding error, and retirees got quietly pushed into more risk than they wanted just to generate income. That math has flipped, and last week’s data is a reason it stays flipped a while longer.
Thomas’ Take: The week’s scary number was the Nasdaq’s 5.5% drop. The week’s useful number was 165,000 jobs — because that’s what keeps your Now bucket and your income floor paying you well. One of those numbers hit a portfolio of expensive growth stocks. The other quietly improved the terms on the part of your plan that buys your groceries. Almost nobody framed the week that way, because “tech crashed” is a better headline than “safe yields held up.”
What a “correction” means inside a bucket plan
Regular readers know I organize retirement money into three buckets, and a week like this one is exactly why. Your Now bucket is the cash and short-term money you’ll spend in the next year or two. Your Soon bucket is your guaranteed income floor — Social Security, pensions, and income-focused instruments that cover your essential bills no matter what the market does. Your Later bucket is the growth money, the equities, the part that’s supposed to ride the waves for a decade or more.
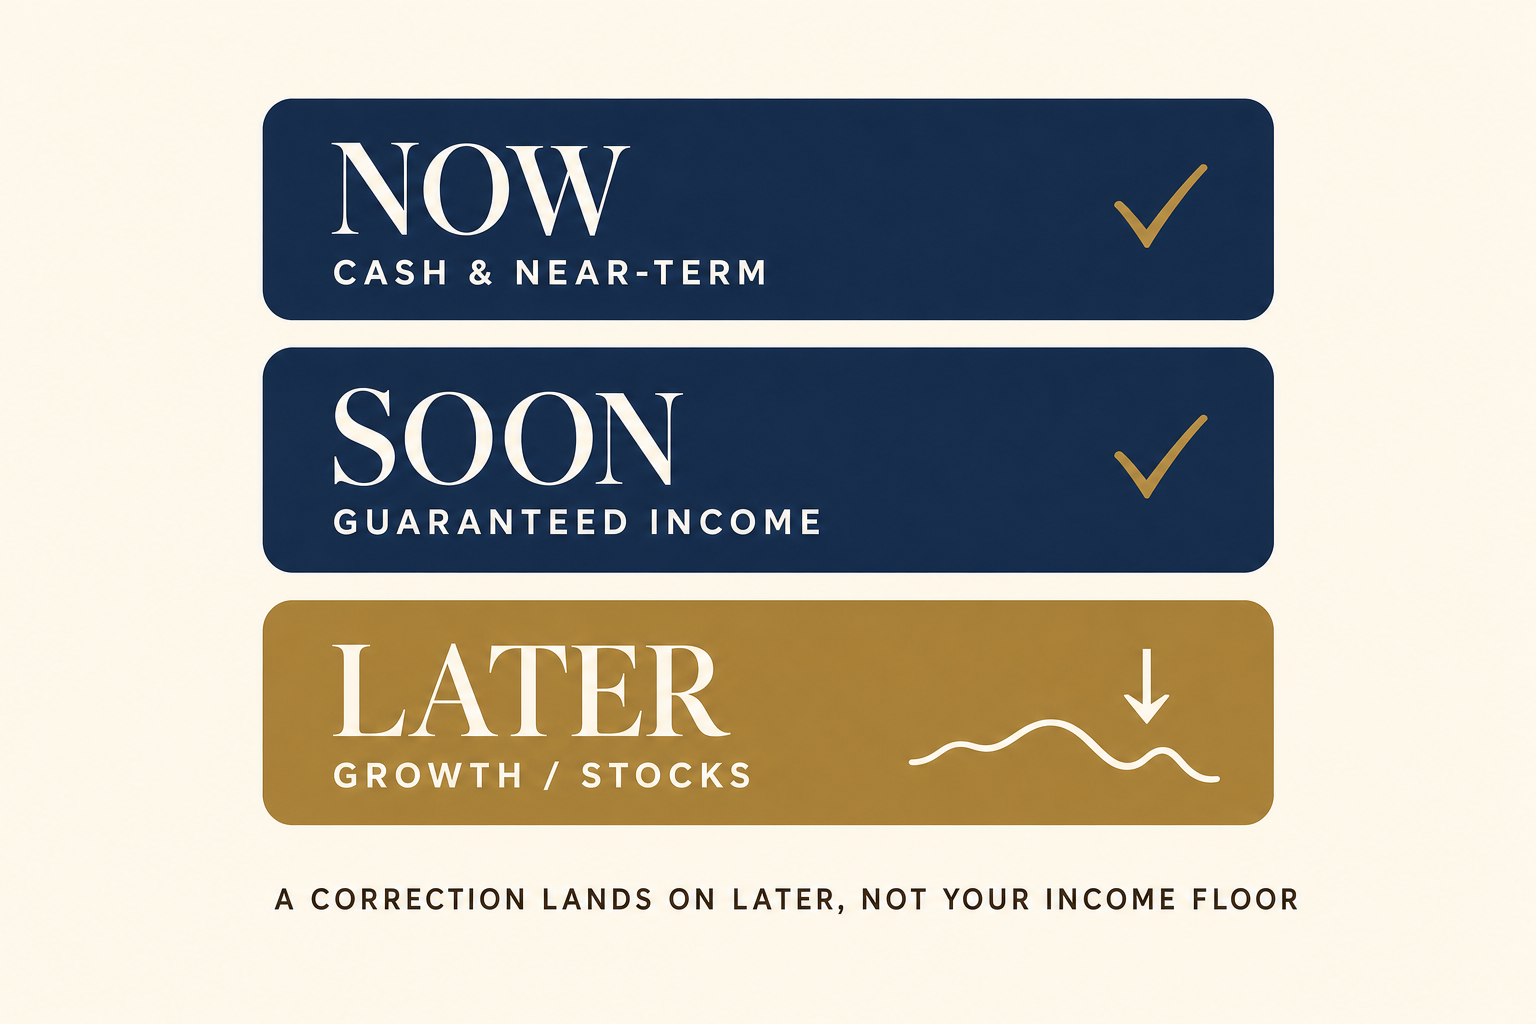
Now map last week onto those buckets. The Nasdaq’s correction lands entirely in the Later bucket. That’s the money with the longest time horizon — the money that should be in stocks precisely because you won’t touch it for years and it has time to recover. Your Now and Soon buckets didn’t flinch. The cash still paid its yield. Social Security still arrived. A fixed index annuity income rider paid exactly what its contract says, which is the whole reason it lives in that bucket.
So the honest question isn’t “how bad was the correction?” It’s “which bucket is my fear coming from?” If a 10% drop in your growth money feels like an emergency, that’s usually a sign the plan is leaning too hard on the Later bucket to do a job the Soon bucket should be doing. A guaranteed income floor is what turns a scary market week into a news story you read rather than a crisis you react to.
Consider a hypothetical case. Margaret, 66, is newly retired with $600,000 in a 401(k) and about $2,900 a month from Social Security. She’s built a Now bucket of two years of expenses in a money market fund paying around 4%, a Soon bucket where Social Security plus a modest annuity income rider covers her essential bills, and a Later bucket of stock funds for everything beyond year three. When the Nasdaq dropped last Thursday, her Later bucket fell on paper. Her grocery money did not move. She is not a forced seller of anything, because nothing she needs this year or next is sitting in stocks. That is the entire design.
If you want to see whether your own buckets are actually built that way, the honest test is to put real numbers on it rather than eyeball it. Map how many years of essential spending your Now and Soon buckets truly cover, then watch what a 10%, 20%, or 30% drop in your Later bucket does to the plan. A tool like ProjectionLab lets you model your own income floor and stress-test it against a market decline, so you find out in a quiet week — not a scary one — whether your plan can absorb a correction without you having to sell anything.
Disclosure: the ProjectionLab link above is an affiliate link. If you subscribe, Confluence Media Group LLC may earn a commission at no additional cost to you. I only point to tools I’d actually use, and this is educational information, not a recommendation to buy any specific investment.
What’s worth doing this week
Three things, none of them dramatic.
First, check which bucket your anxiety is coming from before you touch anything. If it’s the Later bucket, the correct response for money you won’t spend for a decade is almost always to leave it alone. Selling growth assets into a correction to calm a feeling is how a paper dip becomes a permanent loss — the same trap behind why a steady plan shouldn’t flinch at a loud week.
Second, if this week exposed that your income floor is thinner than you’d like, use the elevated-rate environment deliberately. This is one of the better windows in fifteen years to lock in contractual yield in the Soon bucket, and that door doesn’t stay open forever — when the Fed eventually shifts, new money gets worse terms. The flip side is just as real, which is why I keep arguing the Later bucket is where retirees play it too safe: insulating your income lets your growth money actually grow.
Third, don’t over-read one week. The Consumer Price Index comes out Tuesday, November 10, and it will move markets again in one direction or another. A plan built on buckets is specifically designed so that you don’t have to trade around any single data release. That’s the point of building the floor in the first place: so the headlines become something you observe, not something you obey.
The Nasdaq hit a correction last week. If you felt it in your stomach, the fix isn’t to predict the next move. It’s to build a floor sturdy enough that the next correction — and there’s always a next one — lands on the one bucket that was built to take it.
Key takeaways
- The Nasdaq entered a correction last week (down about 11% from its October 6 high), driven by a selloff in a small group of AI megacaps — while the Dow fell less than 1% on the week.
- Friday’s strong October jobs report (about 165,000 jobs, 4.1% unemployment) pushed markets to price in roughly a 3-in-4 chance of a Fed rate increase in December.
- That same “higher for longer” backdrop keeps cash, CDs, Treasuries, and income-rider yields elevated — quietly good news for your Now and Soon buckets.
- A correction lands in the Later bucket, which has the time to recover. A guaranteed income floor is what keeps a loud market week from becoming a personal crisis.
- Before reacting, ask which bucket your fear is coming from — and stress-test whether your income floor actually covers your near-term spending.
This article is published by Confluence Media Group LLC, an independent publisher of educational financial content. Thomas Clark is a Series 65 Investment Advisor Representative. The information provided is for educational and informational purposes only and is not personalized financial, tax, or legal advice. Past performance does not guarantee future results. All investing involves risk, including potential loss of principal. Consult a qualified professional before making financial decisions.
Confluence Media Group LLC is a separate entity from Confluence Capital Management, the investment advisory practice through which Thomas Clark provides advisory services. Advisory services are not offered through this publishing platform.
About Thomas Clark
Thomas Clark is the founder of Confluence Media Group LLC and a Series 65 Investment Advisor Representative. He has spent nearly two decades working with families on retirement planning, with a focus on Social Security optimization, retirement income coordination, and the bucket planning approach to building a guaranteed income floor.
Thomas writes and publishes at thomasclarkadvisor.com and is the author of The Just in Case Binder — a 148-page printable family financial organizer for households who want to make sure the people they love know where everything is.
He lives in North Carolina with his family.
Subscribe to the weekly newsletter · Get the Just in Case Binder

Thomas Clark is a Series 65 licensed investment advisor and experienced trader. He specializes in investing, retirement planning, and market analysis, helping individuals build wealth and make informed financial decisions.
